
MONA VALE FINANCE - A CONCIERGE APPROACH TO PROPERTY FINANCE
You don't have an income problem.
You don't have a rate problem.
You have an access problem.
For self-employed, investors and over 55s who've built real value but still feel the next move is just out of reach.
The cash you need is already there, in what you own.
You've just never had anyone show you how to reach it.
Most brokers walk you through product options. I build you a plan around what you actually own.
Think of it as a concierge approach to property finance. Not just another mortgage broker.
No cost to you. No calls unless you request one.
Most people in your position are asking the wrong question.
They're asking: how do I get a better rate, or how do I earn more?
The better question is: how do I reach the cash I'm already sitting on, in a way that's structured properly?
Because the rate was never the problem. Access was.
Introducing The Access Plan
The Access Plan is how I unlock the cash you're already sitting on, with a clear plan for your next move.
It's not an audit.
It's not a spreadsheet telling you what you already know.
It's not a rate quote dressed up as advice.
It's a clear, honest look at what you've actually got, and the exact moves to turn it into the cash you need. Including second-tier and non-bank lenders that broaden the options available to you.
Think of it as a concierge approach to property finance. Not just another mortgage broker.
What the Access Plan can cover
Not a product list. The situations we plan for.
Self-employed and alt-doc lending
Structured borrowing for business owners using tax returns, BAS, business bank statements, one year in isolation, or accountant's letters.
Equity and cash-out planning
Turning existing property value into usable capital for renovation, business, tax, or family support, with the base protected
Investment property and SMSF finance.
Purchase, refinance, and structure work across bank and non-bank lenders for portfolio owners and first-time investors with equity behind them, including buying investment property inside a self-managed super fund.
Over 55s and family support finance
Options for accessing part of what you own to help children or grandchildren, or to fund the next stage of life, without unwinding the retirement base.
Construction and development finance
Funding for renovations, knock-down-rebuilds, subdivisions, and small development projects where equity in existing property is the starting point for the next build
Refinance and restructure
A second look at existing loans where the structure, split, or lender no longer fits the plan for the next two to five years.
What you walk away with
01
A clear picture of what you're sitting on.
What you already own, and what it could actually do for you.
Not just what it's worth on paper.
Your real borrowing power, across bank and non-bank lenders.
The number a lot of borrowers never see put together in one place.
02
A structured way to reach it.
How much capital may be available to you, and on what terms.
How it should be structured, so it works for you without leaving you exposed.
Your next one or two viable moves, mapped out.
Including second-tier and non-bank lenders that broaden your options.
03
Someone in your corner for the move after this one.
This isn't a one-off transaction. When the next opportunity shows up, you're ready to move on it.
You've got someone who knows your position and has already done the thinking.
I'm here when you want to make the move.
Who's behind mona vale finance
I'm Jess Rawstorne
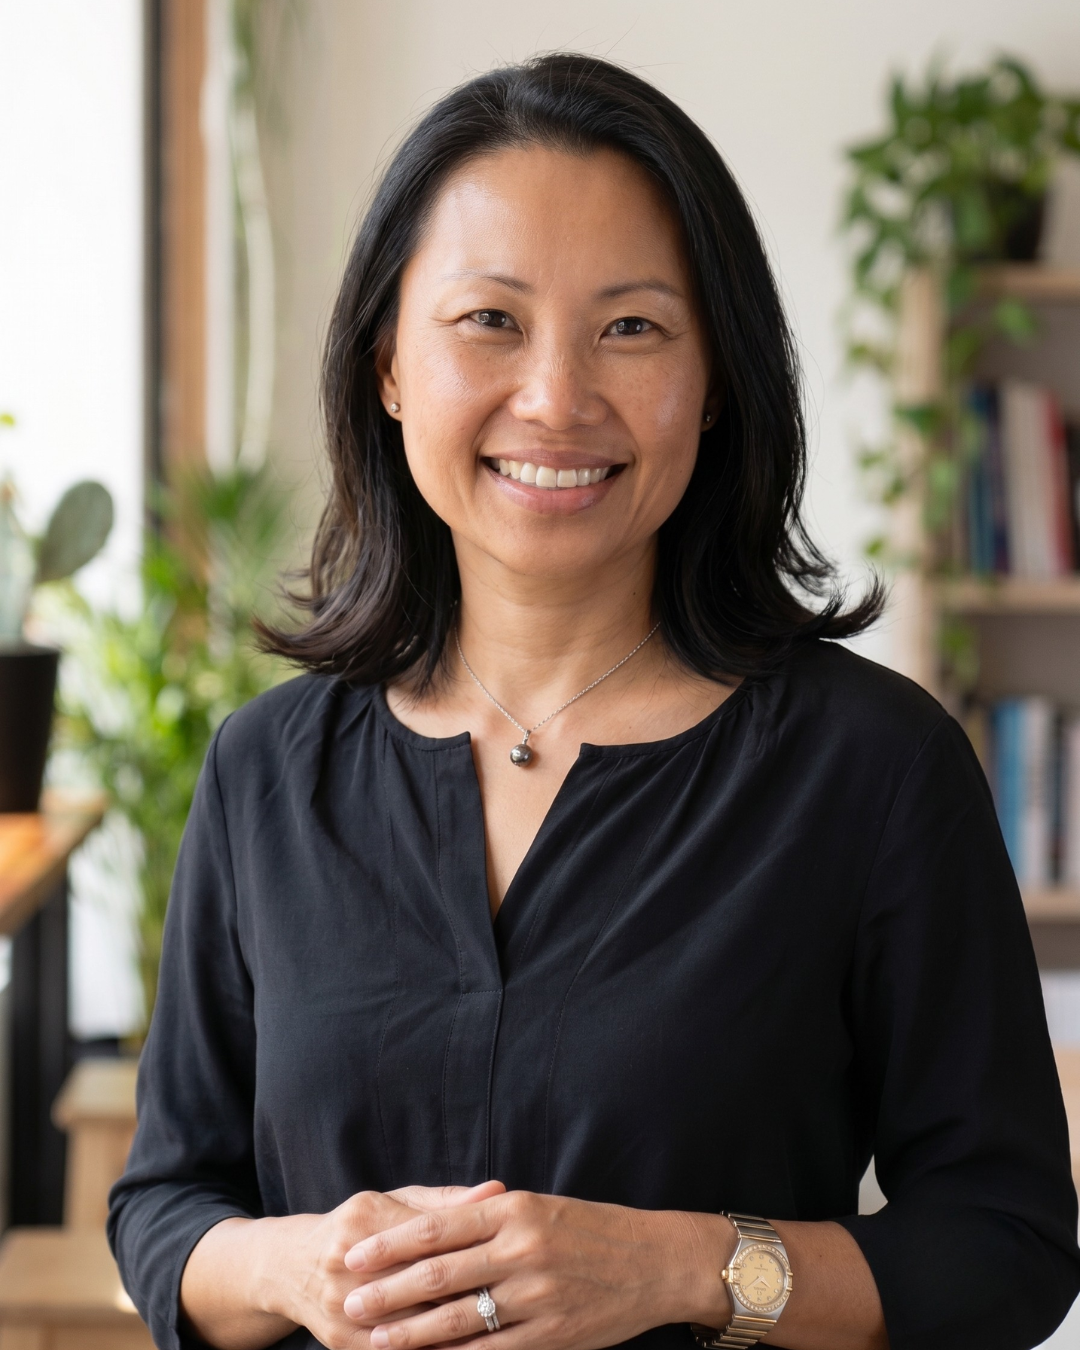
Before Mona Vale Finance, I spent 15+ years in capital structuring and property finance, including a senior role inside a major investment bank, here and overseas. My job was reading files and deciding who got a yes.
What I saw is that good people get a no far more often than they should. Not because the deal was bad. Because it was put in front of the wrong lender, in the wrong shape, at the wrong time.
So I left, and started working for myself. That's now been more than ten years. Long enough to know how a lender reads a self-employed file, and long enough to know how it feels to be the one being read.
Someone who's lived both sides of the desk. In your corner. Not another broker chasing a rate.
Senior 1-on-1 Strategy, Backed by an Established Network
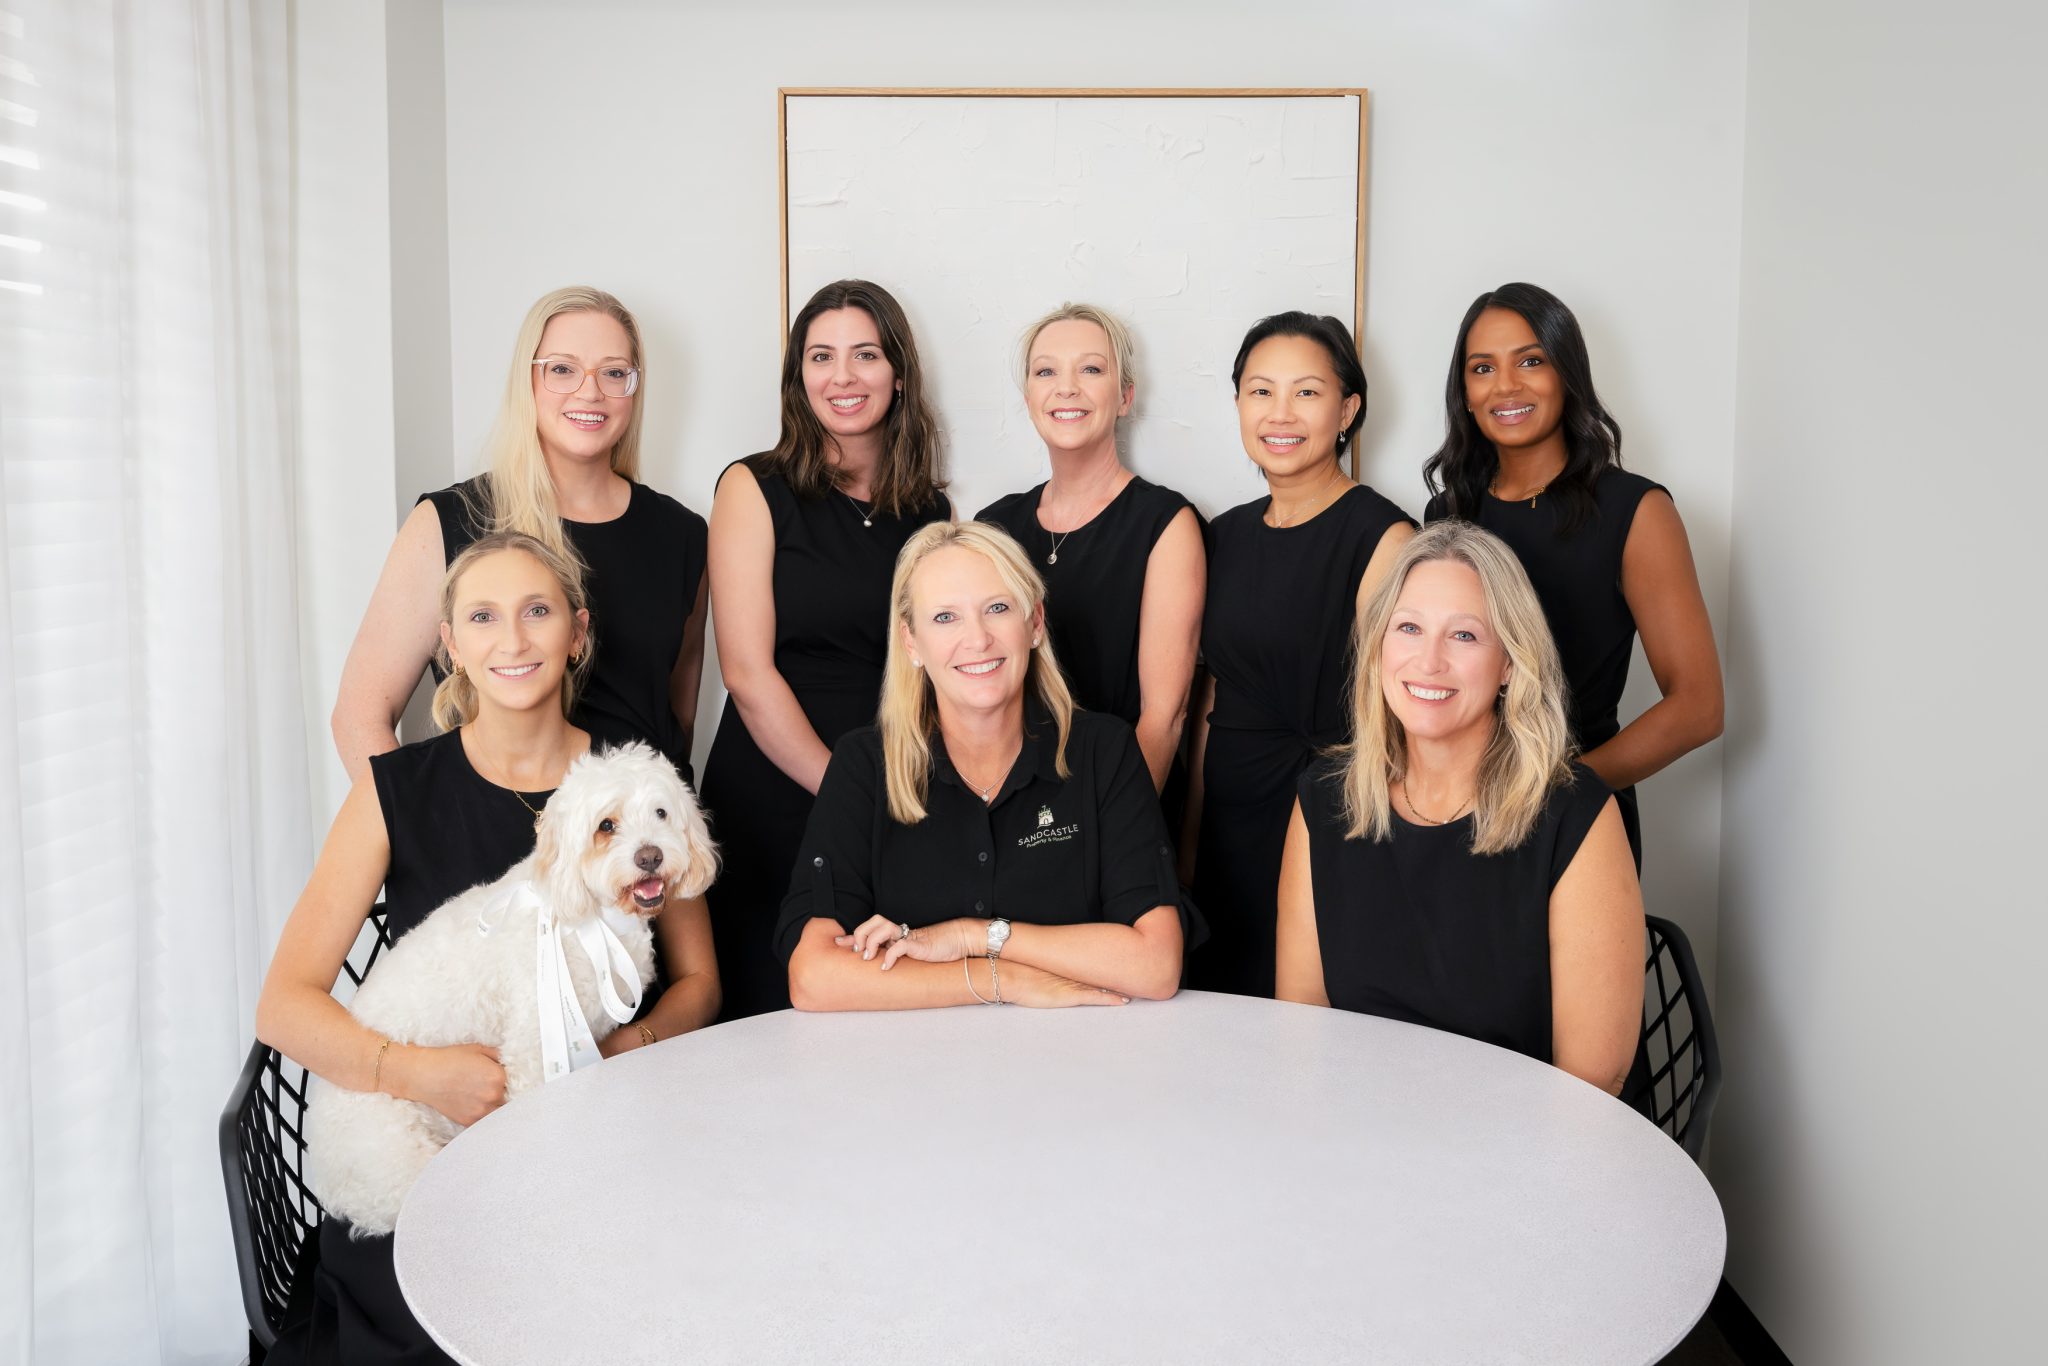
Mona Vale Finance operates in strategic partnership as an authorised sub-broker of Sandcastle Finance.
What does that mean for you?
The concierge approach: 15+ years in capital structuring and property finance, including a senior role inside a major investment bank, brought to your Access Plan from first conversation through to settlement.
Collective strength: You get the full backing, processing speed, and negotiating power of Sandcastle Finance, one of the Northern Beaches' established broking groups.
Broad Lender Access: Access to more than 50 bank, second-tier, and non-bank lenders to find the exact structure that fits your scenario.
Questions I'd ask too
Isn't this just a refinance?
No. A refinance swaps one loan for another. The Access Plan starts with what you own and works out what it can realistically do, then places it. Sometimes that involves a refinance. Not always depending on your individual situation.
Do I have to touch everything I've got?
No. Done properly, you access a portion and leave the base protected. It's not all-or-nothing. That's the whole reason structure matters.
How do I know you're actually on my side and not just chasing a commission?
Because of how clawbacks work. If you're unhappy or refinance away in the first 12 to 18 months, the lender takes back the commission they paid me. So I'm on the hook to put you in the right loan, not just any loan.
What's a second-tier lender? Does that mean dodgy?
No. The big banks are held to APRA policies that cap how much you can borrow. Second-tier and non-bank lenders aren't held to those same policies, which is why they can often stretch your borrowing power. Different rules, not lower standards.
I've been told no before. Does that change anything?
Usually, yes. Most knock-backs happen because the deal was put in front of the wrong lender, in the wrong shape, at the wrong time. Not because the deal was bad. It may have impacted your credit score. But we get to see what the banks see before we approach another lender.
Doesn't every broker say they're different?
Mostly, which is why I don't blame anyone for thinking it. Here's what you can do - Ask whether they've actually sat on the lender's side of the desk, because that's who decides what you can access, and most brokers never have. Then ask whether they're building something that still holds up in two years, or just getting you to settlement. That tells you more than any pitch.
Do I have to jump on a call first?
No. It starts with the guide, then a few quick questions in the lite fact-find. We only talk once there's a real opportunity worth talking about. It respects your time and mine.
My partner would need to be on the loan. Is that a problem?
Not at all. Bring them in. The first step is just a clear picture of what you're both sitting on, so you can make a better call together.
I'm a first home buyer. Can you help?
Honestly, probably not yet, and that's no knock on you. Buying your first place is a great move. It's just not what The Access Plan focuses on. The Access Plan is for people who already own something, a home, a business, an investment property, and want to use what they've got to make the next move. If that's not you yet, get in touch anyway and I'll point you in the right direction.
I'm over 55. Can I use what I own to help my kids or grandkids?
Often, yes, and it's one of the more rewarding parts of what I do. A lot of people your age are asset-rich and want to give the next generation a leg up, a deposit, a hand into their first place, without putting their own retirement at risk. There's usually a safe, conservative way to access a portion of what you own and structure it so the base you rely on stays protected. Careful is not the same as stuck.
And if a direct hand-up isn't the right fit, that's fine too. We look at your individual circumstances, what you own, what you need, and how much certainty you want, and that shapes your own Access Plan. No two are the same, and yours is built around your situation, not a template.
I'm self-employed. My income is inconsistent. Will this still work for me?
Usually, yes, and inconsistent income is one of the most common things I sort out. You've already built something, a business, a home, maybe an investment property. The problem is rarely the income itself. It's how a lender reads it.
The thing most people don't know is there's more than one way to prove your income. Alongside full tax returns, some lenders will look at a year in isolation, your business bank statements, your BAS, or even a letter from your accountant. That's often called alt doc, short for alternative documentation.
Get your Access Plan Guide
If you have read this far, the next step is simple.
Get the guide.
It shows you how The Access Plan works, in plain English.
Then if you want to, we can work out your very own Access Plan.
General Advice Warning
The information provided on this website is general in nature and does not take into account your personal financial situation, objectives, or needs. It does not constitute a credit assessment or offer to lend. Before acting on any information, you should consider its appropriateness to your circumstances and seek independent legal, financial, and taxation advice.
MONA VALE FINANCE
+ 61 485 008 886 | [email protected] | Northern Beaches Sydney Finance Broker
JPak Advantage Pty Limited (ABN 32 137 772 831) trading as Mona Vale Finance; Credit Representative (565995) of Finsure Finance & Insurance Pty Limited (ABN 72 068 153 926) Australian Credit Licence 384704. Sub-broker of Lifestyle Impressions Pty Limited (ABN 15 139 357 109) trading as Sandcastle Finance; Credit Representative (456665) of Finsure Finance & Insurance Pty Limited (ABN 72 068 153 926) .
© 2026 Mona Vale Finance. All Rights Reserved. This content is protected under Australian Copyright Law. Notice of Reservation: All rights to harvest, scrape, or use this content for the purposes of training Artificial Intelligence (AI) models or Large Language Models (LLMs) are expressly reserved. Unauthorised use will be subject to DMCA takedown and legal action.
This site is not a part of the Facebook website, Facebook Inc., Meta Platforms, Inc., or Google LLC. Additionally, this site is NOT endorsed by Facebook or Google in any way. FACEBOOK is a trademark of META PLATFORMS, INC. GOOGLE is a trademark of GOOGLE LLC.